
Universal Asset Owners Daily Brief · Sunday, 6 September 2026
98% of the world’s sovereign wealth funds |
18 of 20 of the world’s largest pension funds |
10 of 10 of the largest charitable foundations |
85% of the world’s largest family offices |
100+ billionaires, every morning |
Watch · Sunday briefing
Sunday 6 September 2026: three tankers taken out of service, gold’s reserve-asset crossover unwound, and the haze that left the forecast.
Chart of the Day
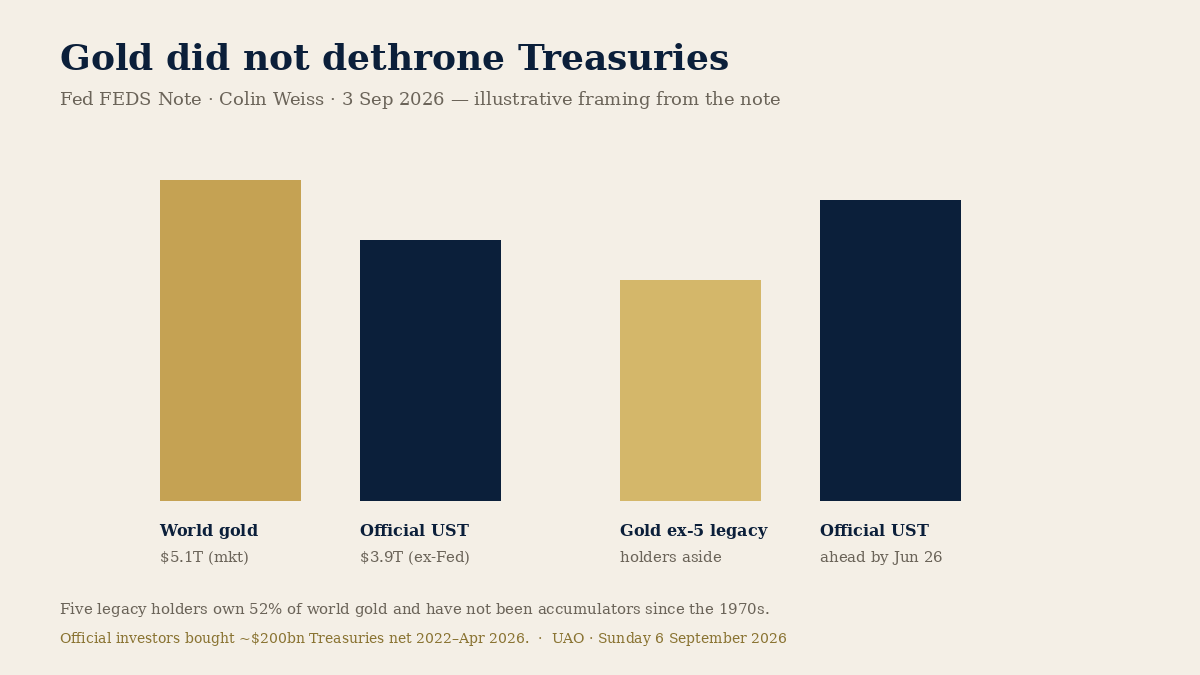
Gold did not dethrone Treasuries
Schematic from the Federal Reserve FEDS Note (Weiss, 3 September 2026): the end-2025 gold-over-Treasuries chart was a price-and-legacy illusion. Once five legacy gold holders are set aside, official Treasuries were ahead again by June 2026.
Opening
Friday’s issue was about permission that did not prove anything: a licence that did not move a shipment, a rating that did not wait for a missed coupon, a bond benchmark that is still only a letter to a ministry. Saturday added a harder fact.
For many commercial flags, the Strait of Hormuz remains effectively closed by war-risk pricing, with throughput a small fraction of the pre-crisis norm. That constraint has not lifted. What changed on 5 September, according to CENTCOM, is the United States treating Iranian export tonnage as a retaliatory instrument. Admiral Brad Cooper’s rule, as quoted by CENTCOM, was arithmetic: two missiles at U.S. ships, three tankers taken out of service. The same CENTCOM release said Iran has no means by which to defend those tankers.
That is not a reason to rewrite Friday’s close in oil. Markets were shut. Three hulls are not Kharg Island. It is a reason to rewrite the scenario tree. The residual risk for universal owners is no longer only “can we insure a transit.” It is whether Iranian fiscal capacity, Gulf redundancy capex, marine IBNR and the inflation path under long-duration liabilities now share a single named-peril: the export fleet.
Two other weekend facts belong next to that tree. A Federal Reserve staff note published on 3 September shows that the 2025 chart in which gold “overtook” Treasuries as the favourite reserve asset was a price-and-legacy illusion — and that official investors were still net buyers of Treasuries into 2026. And South-east Asia’s fire season, flagged here on 4 September as a strong El Niño, has left the forecast and entered the air column over Malaysia, Singapore and the Philippines.
The common error this week is to confuse a document with a cash flow. Do not make it twice.
The Lead
1. The oil fleet is now a target set
What happened
On 5 September U.S. Central Command said the IRGC launched ballistic missiles at a U.S. aircraft carrier and a guided-missile destroyer in regional waters. Both ships evaded the attack. No American personnel were harmed. CENTCOM then said it permanently disabled the crude carriers M/T Downy off Kharg Island and M/T Stark 1 near Jask, and destroyed the unladen M/T Kylo — also called Noxen — in the Gulf of Oman after the crew was directed to abandon ship. Cooper: “If you shoot at two of our ships, we will impose an even higher economic cost — taking out three of yours.” CENTCOM described the three tankers as part of a shadow network that funds the IRGC. IRGC-linked claims of hits on commercial oilers and U.S.-linked vessels are official assertions and have not been independently established.
Why it matters
Insurance already took most commercial flags out of the strait. Saturday adds a second constraint: export hulls can be disabled without a strike on Kharg’s onshore terminals. That hits the cash-flow engine behind IRGC-linked activity, the war-risk and cargo books still reserving last season’s losses, and the fiscal accounts of Gulf owners who must move molecules by pipeline if they move them at all. Every long-duration liability book inherits the inflation path if the energy shock persists.
Underappreciated signal
Washington drew a line under Kharg and over the shadow fleet. That is a choice about escalation control. It is also a signal that “strategic redundancy” — Yanbu, Fujairah, power, water, extra port capacity — is the Gulf allocation decision that survives any single weekend communiqué.
What to watch
- Monday Brent and product cracks; additional-premium quotes; any confirmed commercial-flag casualty; whether the campaign stays on hulls or moves ashore; JWC listed-area language.
Sources. DoD/DVIDS CENTCOM PA (opened), Story ID 574030, 5 Sep 2026: dvidshub.net — confirms Downy / Stark 1 / Kylo (Noxen), Cooper quote, no U.S. personnel harmed, “no means by which to defend them.” CENTCOM mil URL (same release, Access Denied this desk): centcom.mil. IRGC counter-claims remain attributed-only.
Reserves
2. Gold did not dethrone Treasuries
What happened
Colin Weiss, in a Federal Reserve FEDS Note dated 3 September 2026, dismantles the end-2025 comparison that put world gold reserves at $5.1 trillion against $3.9 trillion of foreign official Treasury holdings. World gold includes U.S. gold marked at market prices; Treasury holdings exclude the Federal Reserve. Most of the gold stock was acquired before 1971. Five legacy holders — the United States, Germany, Italy, France and the IMF — own 52 percent of it and have not been accumulators since the 1970s. Once they are set aside, official Treasuries again exceeded gold by June 2026. Official investors bought nearly $200 billion of Treasuries on net from 2022 through April 2026. The 2025 price spike was largely private, including ETF demand.
Why it matters
Boards have been told gold won. If the crossover is an artefact, the reserve-allocation response is mis-specified. This does not cancel last week’s separate observation that the Treasury safety premium has compressed. It says the replacement asset has not, in official books, taken the throne.
What to watch
- Forthcoming TIC; IMF IFS; whether the 10 November rare-earth suspension date produces a visible official-gold spike.
Source (opened). Federal Reserve FEDS Note — Colin Weiss, 3 Sep 2026
Physical print
3. El Niño left the forecast
What happened
Fires in Sumatra and Kalimantan have pushed haze into Malaysia, Singapore and the Philippines. AFP, citing Copernicus CAMS Fire Emissions Watch, put carbon from the fires at more than 23 million metric tonnes from 28 August to 3 September (CAMS portal not opened this desk). Kuching has ranked among the worst-hit Malaysian cities on recent IQAir/API reads — not locked as a Friday global #1. The WMO Air Quality Bulletin is due 7 September.
Why it matters
This publication flagged a very strong El Niño on 4 September. The physical print is here: plantation yields and labour, aviation and ports, crop and municipal insurance, and SE Asian sovereign and consumer exposure.
What to watch
- WMO bulletin, 7 September; direct CAMS portal; burned-area updates; nearby palm oil.
Capital flows
Treat announced, proposed and organizer-claimed figures as what they are.
- SWFI iBRICS, New Delhi, 12–13 September. Organizer claims 500-plus institutions and $1 trillion of AUM in the room, next to the 18th BRICS Leaders’ Summit. Payments-rail sessions (UPI–Pix, CBDC talk) are on the agenda. That is a convening, not committed capital. Watch what, if anything, is signed on 12 September.
- DBSA RFP 157/2026. Feasibility study for a South African Sovereign Wealth Fund and a Pan-African Wealth Fund. Compulsory briefing 8 September 13:00; closes 23 September 23:55. No seed capital announced. Pension market (about R5.6–5.8 trillion) was named as a possible source, not a subscription. dbsa.org/procurement
- Standard Life awarded Ninety One £3 billion of EM equity and Asia ex-Japan active mandates (3 September, IPE).
- Arizona State Retirement System added $600 million to a significant-risk-transfer mandate at BNPP AM Alternatives, taking the relationship to $1 billion (3–4 September).
- Benetton family 21 Next platform: regulatory approvals complete; starts at about €3 billion, aims to exceed €10 billion across PE, energy transition, infrastructure and private debt (Bloomberg, 3 September).
- Chile Superintendencia issued the final generational-fund regime on 1 September; it enters into force on 1 April 2027. Five lettered funds become ten age-based funds. Growth-asset cap starts at 95 percent and declines toward retirement. Primary: spensiones.cl
Still planning, still not raised: PIF-owned Humain’s $2.5 billion data-centre fund remains an unnamed-source Bloomberg account pending CMA approval. Do not treat it as capital deployed.
Risk radar
Where the tail risk sits this weekend
- Further tanker-for-tanker exchanges, or a move ashore at Kharg. Probability: Medium. Impact: High to systemic. Trigger: a confirmed commercial-flag casualty or a strike on Kharg infrastructure.
- 10 November 2026 rare-earth suspension expiry. Probability of a messy lapse: Medium. Impact: High in defence, auto, wind, semiconductors. Licence already does not equal shipment; the dated trigger remains.
- EM pensions pulled toward domestic sovereign paper. Colombia’s Asofondos has offered workers’ savings as a financing tool while a foreign-investment cap is in court; more than 30 percent of the book is already in local public debt.
- SE Asia haze season extending under El Niño. Trigger: WMO bulletin 7 September.
Sustainability and impact
Named-page empty for this Sunday window beyond the haze / El Niño physical print above. No invented item.
Signals — not confirmed
- IRGC assertions of successful hits on commercial or U.S.-linked vessels — attributed only.
- Humain $2.5bn data-centre fund — explores / plans pending CMA.
- iBRICS “$1 trillion AUM in the room” — organizer-claimed.
Careers
None verified in this Sunday window. Cream careers block omitted rather than inventing appointments; roles below are the standing Allocator Desk board, verified open against each employer’s own record on 2026-09-05 and carried forward. Confirm live before applying.
Ontario Teachers' — Managing Director – Private Capital, Software · Toronto, Canada Apply →
BCI — Director, Partnership Portfolio · Victoria, BC Apply →
PSP Investments — Intern, Credit Investments - London (Off-Cycle January–June 2027) · London Apply →
OMERS — Intern, Real Estate Investments (Spring 2027 - January to May) · Singapore Apply →
AIMCo — Student, Economics & Investment Research (May 2027) · Calgary Apply →
Global / Dispatch
Omitted for this Sunday edition — no correspondent filed overnight after the draft locked. The Naveed Iqbal Eurobond ($3bn dual-tranche, event date 3 Sep) remains parked for Monday’s Global edition; it is not re-led here as a Sunday event.
Editorial watchlist
- iBRICS Compact text and attendee list — publish on confirmed names or a close, not the invitation.
- GPIF 21 August committee meeting — calendar anomaly, not an allocation decision.
- Humain CMA file — elevate only on an official notice.
- Korea Hormuz contribution — presidential office: nothing has been decided.
Scenario
Export fleet as named peril
Three IRGC-linked hulls is not a strike on Kharg. The scenario tree still changes: hulls-only, a wider tonnage campaign, or a move ashore are different residuals for Iranian fiscal capacity, Gulf redundancy, marine IBNR and the inflation path under long-duration liabilities.
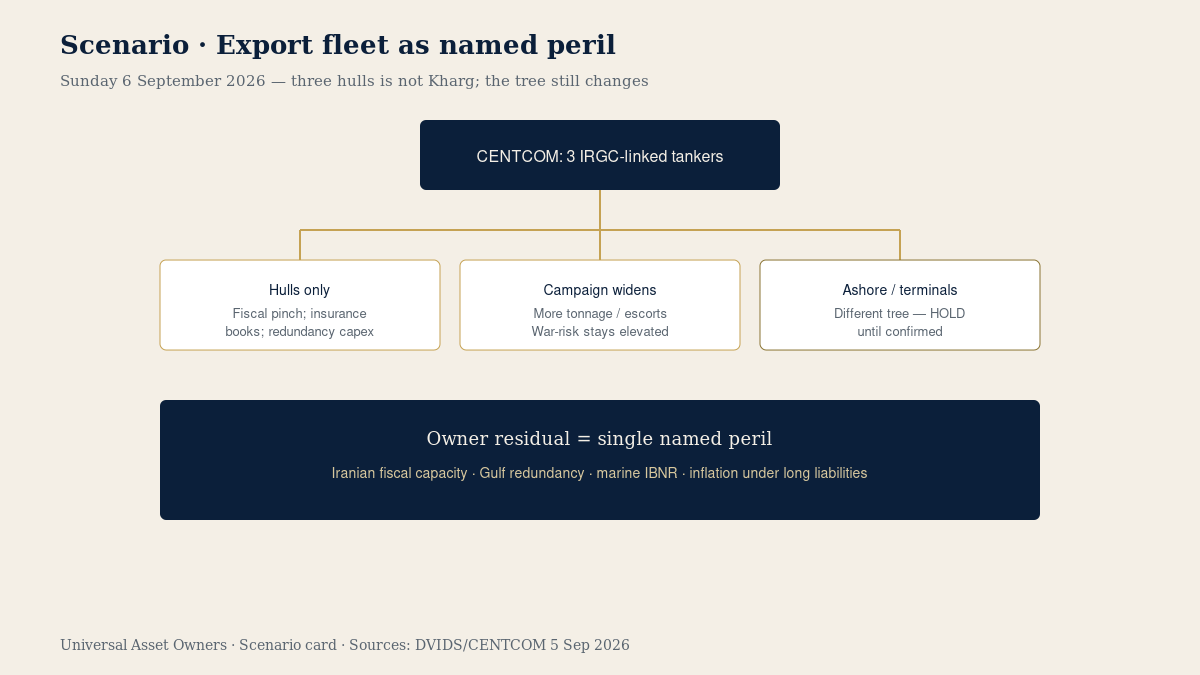
Command Center — verified this pass: the live scenario index (edge API) is not yet refreshed past 4 September; no export-fleet slug is live on Scenario Lab today. Chart above stands in until the index updates. This is a known, flagged gap (edge stuck at as_of: 2026-09-04, no push script exists) — not faked as live.
Podcast · The Universal Owner
“The Oil Fleet Is Now a Target Set” · 6 September 2026
Three tankers taken out of service, gold’s reserve-asset crossover unwound, and the haze that left the forecast — the full edition, spoken.
Listen: The Universal Owner — September 6. Apple and Spotify pull from the same feed and update within the hour.
The Back Page
Meet The Allocator
Sunday 6 September: fifty-two percent — the share of official gold reserves still sitting with five legacy holders who haven’t bought an ounce since the 1970s. Take them out, and Treasuries were back in the lead by June. About 30 seconds.
“Photo finish. Some finishers had help.”
Sources
Source ledger
Primary and first-party
- DoD/DVIDS CENTCOM PA, Story ID 574030, 5 Sep 2026 — opened; primary for Downy/Stark 1/Kylo(Noxen), Cooper quote.
- centcom.mil Article/4591744 — same release, dual-cite URL (Access Denied this desk).
- Federal Reserve, FEDS Note, Colin Weiss, 3 Sep 2026 — opened.
- DBSA RFP 157/2026 (dbsa.org/procurement) — opened.
- Chile Superintendencia de Pensiones, generational-fund regime notice — opened.
Reporting (primary or first-party sources used where available; wire copy is not treated as a primary source)
- AFP, citing Copernicus CAMS Fire Emissions Watch — Sumatra/Kalimantan fire emissions tonnage (CAMS portal itself not opened this desk).
- IPE — Standard Life / Ninety One EM equity mandate.
- Bloomberg — Benetton family 21 Next platform; Humain data-centre fund (unnamed-source account, pending CMA).
Sources checked through 6 September 2026. Material claims are linked to named sources; primary or first-party sources are used where available. Hormuz day-count and war-risk premium multiples remain held pending an opened insurance primary.
Also on UAO
Permission Is Not Proof — Saturday Daily Brief (5 Sep).
Daily Brief archive — weekday intelligence.
The Long Horizon Weekly — Sunday magazine hub.
UAO Insider — weekend talent / who-moved.
UAO Fiduciary — Wednesday ESG edition.
UAO Live — last Friday show: When Real Assets Can’t Deliver | Panama, Power & Portfolio Risk.
Watch hub — briefing video archive.
Universal Asset Owners · The Editorial Team. Capital at the scale of the world. Research and analysis for the institutions investing at that scale. Not investment advice.