The implementation gap becomes the investment case
China's factory pulse slips below 50 as COP17, power consolidation and the EU–Canada alliance move from strategy toward delivery.
Good morning. Today's issue follows the final span between institutional ambition and operating cash flow.
Watch the Latest UAO LIVE with Ryan Lafield
Ryan Lafield separates the headline strength of the US economy from the pressures households feel—useful context for portfolios balancing aggregate growth, labour income, consumption and political risk.
Watch the Latest EpisodeSix signals for the whole balance sheet
China: official October manufacturing PMI fell to 49.3; non-manufacturing and composite activity were both 49.7. [1]
Nature: COP17 closed with the Yerevan Pathway and nearly 50 decisions; announced finance is not the same as capital deployed. [3]
Power: Vistra completed its Cogentrix acquisition, adding ten plants and 5,496 megawatts alongside competition-related divestment commitments. [4] [6]
Canada: August industry GDP was unchanged and September's advance estimate pointed to a 0.1% decline. [2]
Alliance: the EU and Canada opened work across digital trade, critical resources, compute, subsea cables, ports and energy security. [7]
Governance: ESMA warned that shrinking the sustainability board could weaken diversity and expertise. [8]
The implementation gap becomes the investment case
China's October purchasing managers' surveys put the implementation problem in one frame. Manufacturing registered 49.3, production 49.8 and new orders 49.4. Export orders were weaker at 48.7. Large firms remained just above 50 at 50.2, while medium and small firms were below it at 48.4 and 47.5. [1]
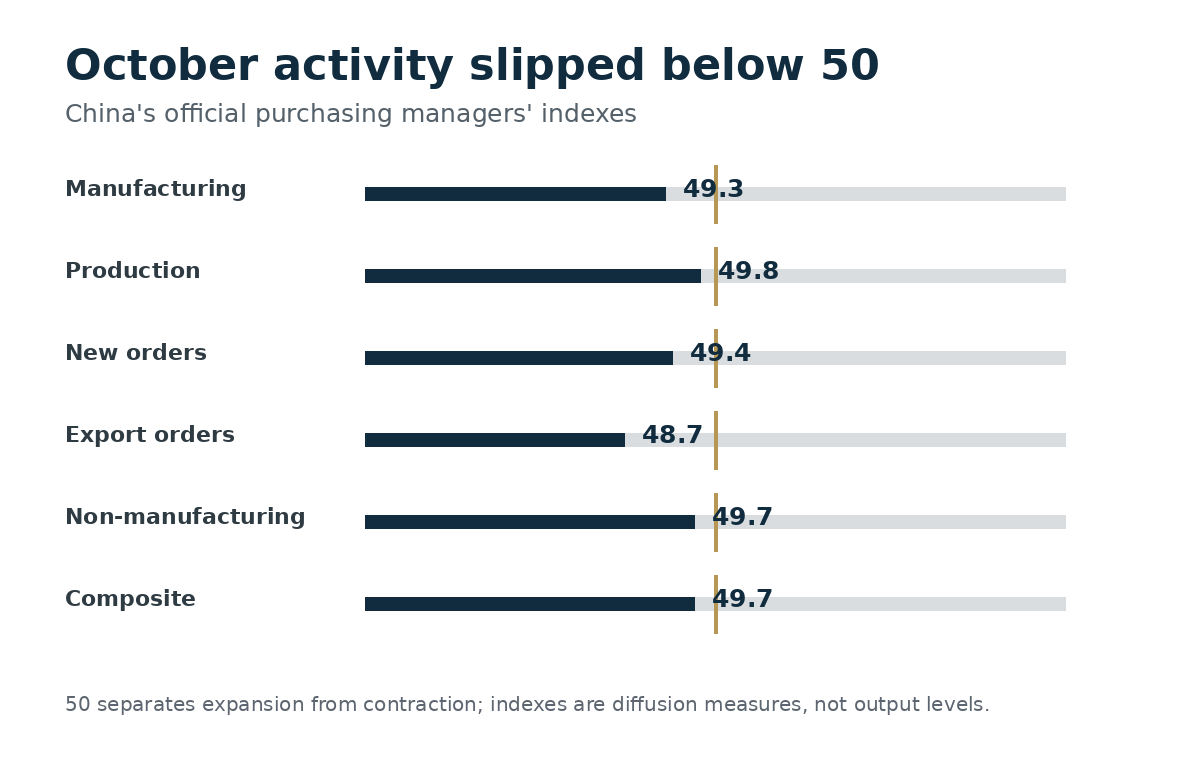
The figures are diffusion indexes, not output levels, but the breadth matters. Investors are underwriting a major physical buildout in power, data centres, ports, grids and industrial capacity while the factory pulse is soft and uneven. The opportunity lies in the gap between strategic intention and delivered capacity; the risk is paying for policy ambition before orders and utilisation arrive.
Three fresh developments illustrate that divide. COP17 produced the Yerevan Pathway and almost 50 decisions. Vistra completed a 5.5-gigawatt acquisition while a related plant disposal remained pending. The EU and Canada agreed new workstreams spanning critical resources, compute and trade corridors. Each moves from narrative toward implementation, but none removes permitting, governance, funding or demand risk. [3] [4] [6] [7]
The countercase is that weak purchasing-manager readings can reverse quickly, and strategic programmes may unlock private investment before current demand data improves. The falsifier is operating evidence: orders, connections, throughput, cash flow and distributions—not another announcement.
China and Canada warn against reading policy as demand
China's non-manufacturing PMI and composite index both stood at 49.7 in October. High-technology manufacturing, at 51.3, and equipment manufacturing, at 50.6, offered a stronger pocket, but small manufacturers remained at 47.5. [1]
Statistics Canada reported that August real GDP by industry was unchanged. Services contracted 0.1% while goods-producing industries grew 0.1%; the advance estimate for September pointed to a 0.1% decline, alongside a preliminary 0.3% increase for the third quarter. Advance estimates remain subject to revision. [2]
For a universal owner, the shared transmission channel is utilisation. Infrastructure, logistics and industrial exposures can receive policy support while cyclical demand stays soft. A resilient portfolio distinguishes contracted revenue from volume-dependent revenue and avoids counting the same recovery across public equity, private assets and credit.
Korea's chip exports offer a contrasting demand signal
South Korea's trade ministry reported on 1 November that October exports rose 93.7% year on year to US$115.28 billion, the second-highest monthly total. Exports per working day rose 76% to US$5.24 billion; semiconductor exports increased about 259%, while non-chip exports grew 34%. The working-day comparison tempers the headline surge without erasing its strength. [17]
For allocators, this is a counterweight to China's weak survey readings: technology demand is strong, but the chip cycle should not stand in for the whole industrial economy.
Vistra closes; the remedy is part of the economics
Vistra completed its Cogentrix acquisition on 30 October, adding ten plants with 5,496 megawatts of capacity and taking the combined generation fleet to nearly 50 gigawatts. The transaction was initially described in January at an approximately US$4.0 billion net purchase price, comprising cash, stock and assumed debt after estimated tax benefits. [4] [5]
The US Department of Justice said Vistra sold Casco Bay and that the parties also agreed to sell Rumford. It said it would continue monitoring the Rumford sale and anticipated annual consumer savings in the tens of millions of dollars from the divestments. [6]
Completion is the relevant stage: the portfolio now carries operating, commodity, capacity-market and integration exposure. The remedies are not a footnote. The completed Casco Bay sale and planned Rumford disposal show how regulatory structure can change the eventual asset perimeter and become a core underwriting variable in power consolidation.
Aramco closes its HUMAIN investment
PIF and Aramco announced on 1 November that their HUMAIN transaction had closed. Aramco acquired 49% through a subsidiary and PIF retained 51%. The transaction includes AI and digital assets plus approximately SAR9.9 billion (US$2.6 billion) in Aramco cash contributions during 2026. HUMAIN plans 3 gigawatts of AI data-centre capacity by 2030; that capacity remains a deployment target. [18]
The ownership transaction is complete. The next investment test is whether power, customers and construction can turn the planned compute capacity into operating revenue.
The EU–Canada alliance turns toward physical and digital corridors
The EU and Canada said they had concluded substantive negotiations on a digital trade agreement. They welcomed Canada’s EuroHPC participation and outlined further cooperation on critical resources, AI factories and compute capacity, subsea cables, ports, payments and capital flows. They also agreed to assess LNG opportunities. [7]
The wider alliance is a cooperation framework, not an aggregate investment commitment. Its institutional value is the map of shared dependencies: data, power, minerals, maritime routes and financing architecture. The opportunity is diversified supply and interoperable infrastructure. The countercase is execution across jurisdictions with different procurement, permitting and industrial-policy regimes.
COP17 moves biodiversity from targets toward national machinery
COP17 concluded with the Yerevan Pathway, the first collective review of progress under the Kunming–Montreal Global Biodiversity Framework and nearly 50 decisions. The final release highlighted faster action on harmful incentives and the integration of biodiversity into national budgets and economic decisions. [3]
Announced funding approached US$2 billion, including US$560 million linked to GEF-9 and the Global Biodiversity Framework Fund, a US$500 million Species Recovery Alliance and more than US$330 million for the Value Nature Fund. These are announcements, not proof of deployment or outcomes. [3]
The allocator question now shifts from policy coverage to investable delivery: which national plans alter cash flows, permits, land use or liabilities, and which remain reporting exercises? Stewardship should test governance, baseline quality and capital expenditure rather than treat a COP decision as a portfolio outcome.
Who governs the sustainability standards?
ESMA supported a smaller sustainability board in principle but said ten members should normally be the lower bound and warned that eight could weaken diversity and expertise. It also sought stronger safeguards for at-large appointments, investor and regulator representation and six affirmative votes for decisions rather than five. [8]
This is a consultation response, not an adopted constitutional change. The whole-balance-sheet issue is legitimacy: standards that shape reporting and valuation must be governable across markets and jurisdictions. A leaner body may decide faster; an underspecified body can lose the expertise and representation needed for adoption.
Strategic designations still need financial close
Canada designated Roberts Bank Terminal 2 as a project of national interest, describing a C$5.9 billion container-terminal expansion with a target final investment decision in mid-2027 and operations in 2035. Designation is not final investment decision or deployed capital. [9]
The Canada Infrastructure Bank separately reached financial close on a C$30 million, 27-year loan to Enoch Cree Nation for housing-enabling infrastructure supporting approximately 166 homes. [10]
These examples sit at different stages: one is a strategic pathway; the other is a financing close. Committees should resist adding them into a single “infrastructure investment” total. The relevant questions are conditions precedent, construction risk, user demand and the route from enabling works to economic use.
A delivery mandate at Samruk-Energy
Samruk-Kazyna appointed Ansar Aidarov Chairman of the Management Board of Samruk-Energy. The official announcement cited his prior investment and project-office roles and framed the mandate around project delivery. [11]
For state-linked energy groups, leadership changes matter when they alter capital allocation, execution accountability or the pace of major projects. The evidence to watch is not the appointment itself but milestone disclosure, procurement discipline and operating performance.
Where implementation can break
Industrial demand — probability medium-high; impact high. Confirmation: new orders and export orders remain below 50 while capacity expands. Disconfirmation: broad-based order recovery and rising utilisation.
Nature finance conversion — probability medium; impact medium-high. Confirmation: commitments fail to reach investable projects or measurable outcomes. Disconfirmation: funded national plans with credible baselines and reporting.
Power-market concentration — probability medium; impact high. Confirmation: further remedies or price pressure in constrained regions. Disconfirmation: competitive entry, transmission buildout and stable capacity markets.
Alliance execution — probability medium; impact high. Confirmation: frameworks stall before finance, permits and procurement. Disconfirmation: signed agreements, financial close and operating assets.
What changes the thesis
China: the next official new-orders and small-firm readings will test whether October was temporary or broadening weakness. [1]
Canada: revisions to the August and September GDP path will test the preliminary third-quarter signal. [2]
Vistra: integration disclosure and regional market data will show whether the acquired fleet earns through the regulatory remedy. [4] [6]
COP17: national budget changes, capital calls and measurable outcomes will distinguish announced finance from delivery. [3]
Four documents for the committee pack
China's October PMI release: the firm-size and subindex detail behind the 49.3 headline. [1]
COP17 final release: the decisions, finance announcements and implementation architecture. [3]
EU–Canada joint statement: a whole-system inventory of digital and physical chokepoints. [7]
ESMA's IFRS Foundation letter: a concise case study in standards-setter governance. [8]
Own the bridge, but underwrite the final span
The weekend tape is rich in strategic intent: a nature pathway, a transatlantic alliance, a nationally important port and a power acquisition. The common risk is assuming that institutional intent is already operating cash flow.
The best investment case may lie in closing the gap—power, logistics, compute, standards and project finance. The best risk control is stage precision. Designation, negotiation, commitment, financial close, completion and utilisation are different assets on the way to the same headline.
Original reporting and documents
[1] National Bureau of Statistics of China — Purchasing Managers' Index for October 2026
31 October 2026
[2] Statistics Canada — Gross domestic product by industry, August 2026
30 October 2026
[3] Secretariat of the Convention on Biological Diversity — COP 17 concludes with the Yerevan Pathway
31 October 2026
[4] Vistra — Vistra completes acquisition of Cogentrix Energy
30 October 2026
[5] Vistra — Vistra adds Cogentrix to generation portfolio
5 January 2026
[6] US Department of Justice — Statement on Vistra's acquisition of Cogentrix
30 October 2026
[7] European Council and Government of Canada — Joint statement on the EU–Canada Alliance
30 October 2026
[8] European Securities and Markets Authority — Targeted amendments to the IFRS Foundation Constitution
30 October 2026
[9] Transport Canada — Roberts Bank Terminal 2 listed as a project of national interest
30 October 2026
[10] Canada Infrastructure Bank — CIB to loan Enoch Cree Nation C$30 million for housing-enabling infrastructure
30 October 2026
[11] Samruk-Kazyna — Ansar Aidarov appointed Chairman of Samruk-Energy
30 October 2026
[16] Universal Asset Owners — U.S. Economy Booming? Why Americans Aren't Feeling It | UAO Live Ep. 55
30 October 2026
[17] South Korea Ministry of Trade, Industry and Resources — October 2026 export and import trends
1 November 2026
[18] Aramco — PIF and Aramco close HUMAIN transaction to accelerate HUMAIN's global growth
1 November 2026
The final span
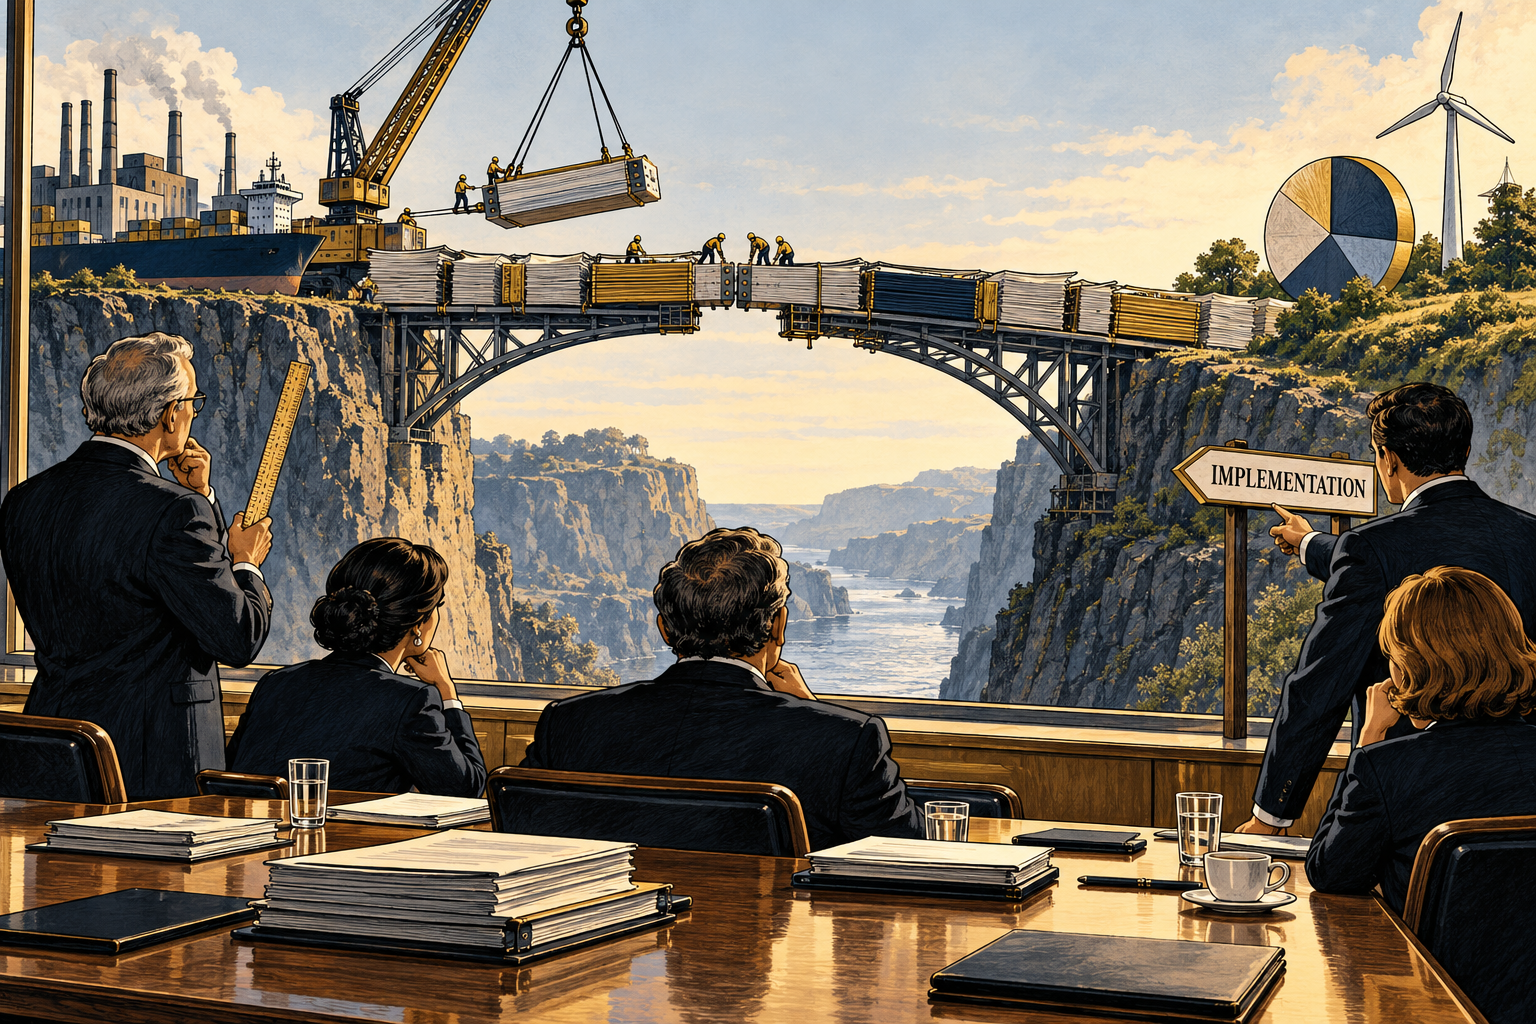
The committee had approved the bridge, celebrated the bridge and allocated to the bridge. The construction crew was still tightening the final bolts.